
How can parents stop and report screen sharing fraud on their children
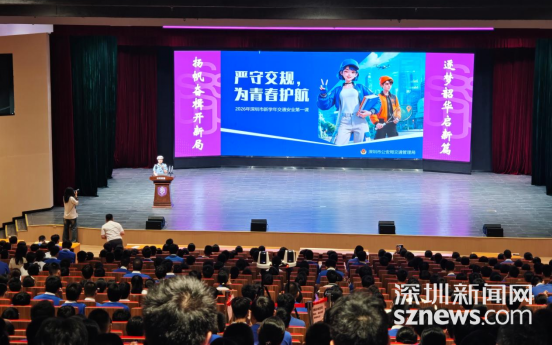
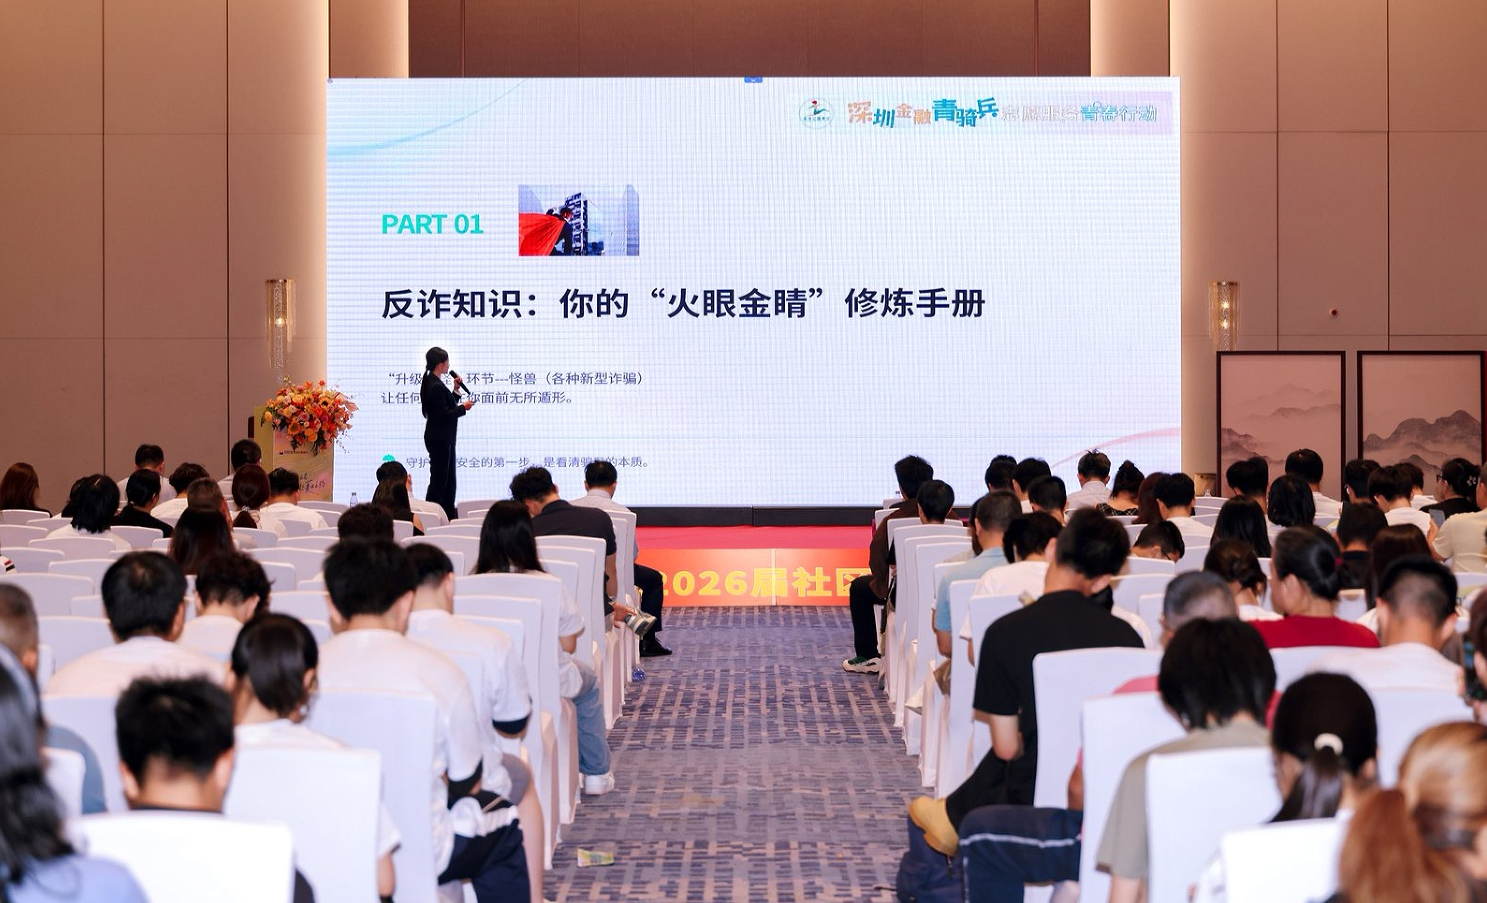
On August 14, 2026, the "Green Cavalry" volunteer service team of Shenzhen Rural Commercial Bank Gongming Branch entered the community and held an anti fraud lecture for students and parents in the jurisdiction, focusing on scams targeting teenagers such as screen sharing, brushing orders for rebates, and impersonating teachers to charge fees. Behind such activities is a reality: electronic fraud is spreading to younger age groups, and parents often do not know where to start to protect their rights afterwards. As a Shenzhen lawyer who has been dealing with fraud cases for a long time, I believe that in addition to pre emptive prevention, the legal path after the fact should also be clear - if the money is transferred, what is the basis for recovery? Are banks and platforms responsible? This article combines the relevant provisions of the Civil Code and the Anti Telecom Network Fraud Law to provide a set of guidelines for Shenzhen families to follow.
Legal characterization of screen sharing fraud: why it is difficult to pursue
The tricks of this type of scam are: scammers lure children to turn on screen sharing by giving them game skins, part-time brushing orders, or impersonating teachers to collect data fees, allowing them to see their bank card numbers, payment passwords, and SMS verification codes in real time, and then remotely transfer funds. Legally speaking, this is a typical telecommunications fraud and may constitute the crime of fraud under the Criminal Law.
But in practice, parents often encounter two difficulties after reporting to the police. Firstly, if the person is overseas, the funds can be quickly split and withdrawn through multiple accounts, resulting in high investigation costs; The second is that children are afraid of being scolded, often taking several days or even weeks to say, and when parents find out, the window for freezing and stopping payments has already passed. So the top priority for such cases is not waiting to be solved, but to quickly initiate two lines of civil rights protection and administrative complaints.
Another point that is often overlooked is that if a bank fails to verify its identity and trigger a risk warning during the transfer process, according to the provisions of the Civil Code on fault liability, the bank may bear corresponding compensation liability. But it is not easy for parents to prove that the bank is at fault in practice, and they need to retrieve transaction records, risk control rules, account abnormal prompt records and other materials.
There are three paths that parents can take: reporting to the police, stopping payments, and civil litigation
One is to immediately report to the police and apply for emergency payment suspension.According to the relevant provisions of the Anti Telecommunications Network Fraud Law, public security organs should quickly activate the stop payment mechanism upon receiving a report. Parents should prepare transfer records, chat screenshots, and screen sharing operation records, and clearly inform the involved account information. The anti fraud center in Shenzhen has a linkage mechanism with banks, and the earlier the alarm is reported, the greater the possibility of freezing.
The second is to apply to the bank to cancel the transfer.According to the relevant regulations of payment settlement, if the transfer occurs within a short period of time and can be proven to be fraudulent, the bank can assist in processing it. But screen sharing scams often involve real-time payment, and when parents discover it, it often exceeds the time limit. The applicability of this path is limited, and we cannot place all our hopes on it.
Thirdly, file a civil lawsuit.If the money cannot be recovered, according to the provisions of the Civil Code on revocability of fraudulent behavior, the transfer behavior can be requested to be revoked on the grounds that the child has been defrauded, and the payee can be required to return the funds. The prerequisite is to be able to lock the subject of the receiving account. In practice, the receiving account is often a "head account" used by others, which is difficult to execute. At this point, both the payee and the cardholder can be listed as defendants, claiming that the act of lending or selling the account constitutes joint infringement - this type of lawsuit may not necessarily be able to recover all the money, but it can increase the pressure on the other party, and there are also precedents supporting the cardholder to bear partial responsibility.
The responsibility boundary between the platform and the school
Social media and payment platforms are often used in such cases. According to the relevant provisions of the Cybersecurity Law and the Anti Telecommunications Network Fraud Law, network service providers have the obligation to monitor and dispose of fraudulent information. If the platform fails to intercept obvious abnormal sharing requests or fraudulent links in a timely manner, it may face administrative penalties; But civil claims require proof that the platform "knew or should have known", which is a high threshold.
In terms of schools, if scammers impersonate teachers to charge fees in class groups and fail to fulfill their group management obligations, according to the provisions of the Civil Code on security obligations, they may bear partial responsibility. But such incidents often occur in groups spontaneously established by parents, not on campus, and school responsibility is generally difficult to establish. Instead of being fixated on schools, it's better to focus on two things: one is to complain to the Shenzhen Branch of the People's Bank of China and the Shenzhen Regulatory Bureau of the State Financial Supervision Administration about relevant banks or payment institutions, and demand that they fulfill their anti fraud obligations; The second is to use the rectification or punishment results obtained from the complaint as evidence in civil litigation.
Four suggestions for parents in Shenzhen
One is to turn "money matters" into household rules.Make an agreement with the child that any operation involving payment, scanning codes, or sharing screens must be asked to the parents in person first. At the same time, turn off the default permissions for screen sharing and remote assistance functions on your phone, and regularly check your child's payment records.
The second is to fix the evidence after the incident.Take screenshots of chat records, transfer vouchers, other party accounts, shared screen operation logs, and timelines, and save them all. Do not rush to delete the other party's account, nor do you argue with scammers on your own. The evidence is there, and there will be a basis for reporting and prosecuting later.
The third is to make good use of programming tools.For those with significant losses, they can apply for property preservation and freeze the involved account during the lawsuit; At the same time, lawyers can be entrusted to inquire with the public security organs about the filing situation and promote criminal proceedings. Administrative complaints and civil lawsuits can be filed simultaneously without waiting for criminal results.
Fourthly, do not blame the child.The more afraid a child is, the less they say, and the less money they can recover. First, clarify the timeline before discussing responsibility.
Guangdong Zhiming Law Firm has long been concerned about online fraud and the protection of youth rights, and has handled emergency payment suspensions, civil litigation, and criminal reporting guidance. If you encounter a similar situation, you can bring all the materials to Room 1802, Building A, Xintian Century Business Center, Shixia North Second Street, Futian District, Shenzhen for a face-to-face meeting. The phone number is 0755-25986969. The earlier you act, the more money you can save.