
2026 Financial Education Awareness Week Observations: Banks Bring Legal Knowledge to Stations, Shenzhen Lawyers Explain Paths for Financial Consumer Rights Protection
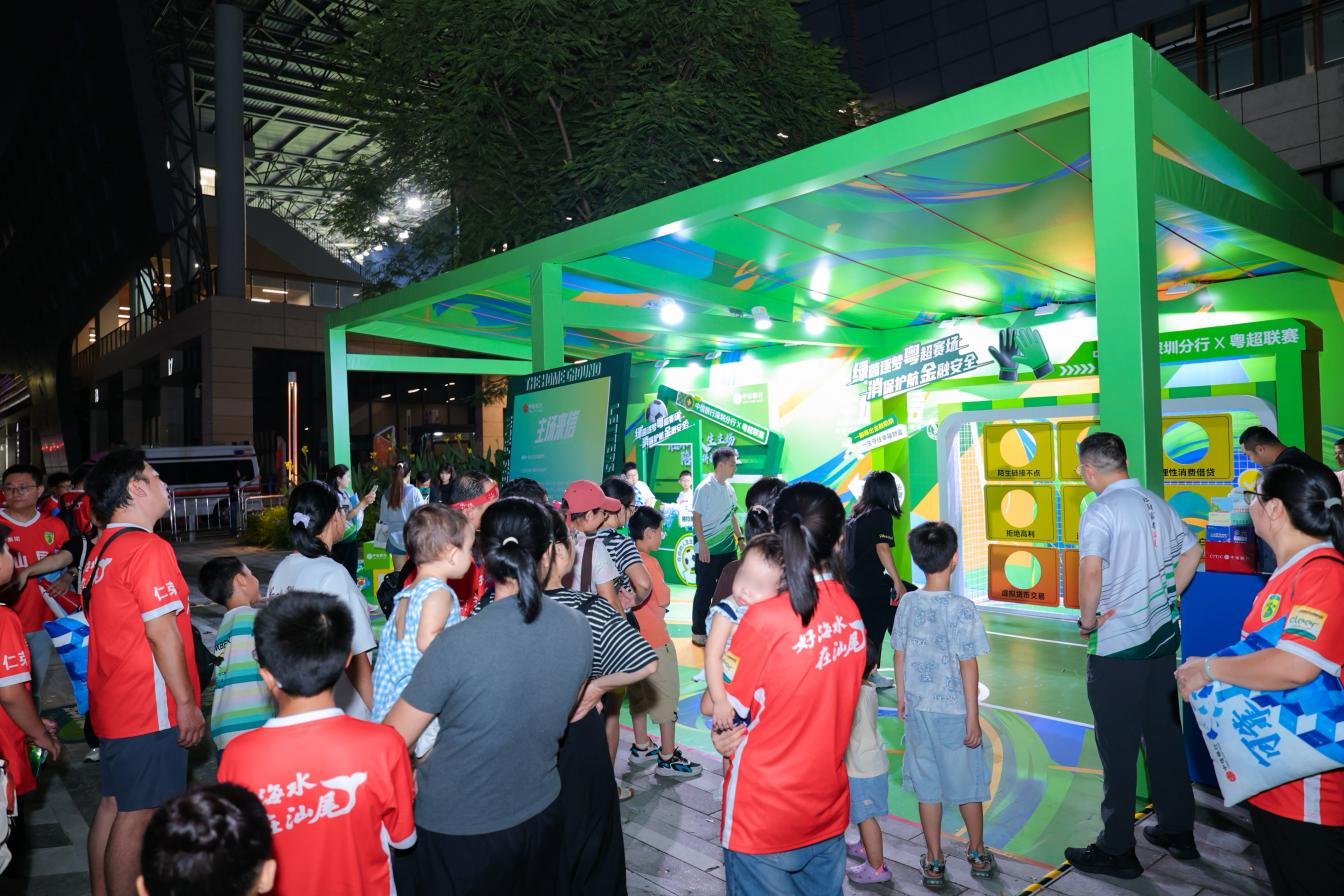
In September 2026, China CITIC Bank launched Financial Education Publicity Week nationwide. From Chongqing charging stations to Shenzhen Guangdong Super League venues, from Harbin senior singing and dancing competitions to bilingual anti-fraud classes in Liangshan Yi villages, it packed financial consumer protection knowledge into ride-hailing driver stations, courier stations, and school classrooms. This education campaign, called for by regulators and implemented by financial institutions, appears on the surface to be public-interest education, but its underlying logic points to an increasingly acute reality: financial consumer disputes are spreading from “large-amount wealth management blowups” to “small-amount, high-frequency scams.” What ordinary people’s wallets face is not a single risk, but scenario-based, fragmented extraction. As Shenzhen lawyers who have long handled financial disputes, we are more concerned about this: when the education campaign ends and scams still occur, what weapons does the law leave to financial consumers, and how should ordinary people use them?
The Legal Signal Behind Financial Education: Consumer Protection Has Shifted from Advocacy to Obligation
Banks go to great lengths to create anti-fraud brochures, financial literacy radio programs, and delivery-rider stations, not merely for branding. The Implementation Measures of the People's Bank of China for the Protection of Financial Consumers' Rights and Interests, effective in 2020, explicitly require financial institutions to disseminate financial knowledge, and the Measures for the Administration of Consumer Rights and Interests Protection of Banking and Insurance Institutions issued by the former China Banking and Insurance Regulatory Commission in 2022 further make consumer education a statutory obligation of institutions rather than an optional public-interest undertaking. In other words, financial institutions must not only sell products but also be responsible for consumers' cognitive ability.
This shift is of great significance to ordinary people. In past financial disputes, consumers often lost their cases because of “signature confirmation” and “assumption of risk”; now courts and regulators
For Shenzhen lawyers, this means that the focus of a category of cases is shifting: it is no longer only about arguing over “what the contract says,” but about examining “what the institution did and did not do.”
Legal Characterization of Three Types of High-Incidence Scams: From Credit Repair to Agency Policy Surrender
The scams repeatedly highlighted during Publicity Week actually each have clear paths for legal characterization, and ordinary people may wish to identify them by comparison.
The first category is credit repair and credit cleansing. There is no internal deletion channel in the central bank credit reporting system, and any intermediary claiming that paying money can eliminate adverse records is essentially committing fraud. Under the Regulations on the Administration of the Credit Reporting Industry, credit reporting agencies must retain an individual’s adverse information for five years; after that period it shall be deleted, with no fee required. If an intermediary collects a fee and then becomes unreachable, one may report it as fraud under Article 266 of the Criminal Law; if an intermediary induces consumers to forge materials to file an appeal with a bank, the consumers themselves may be suspected of forging certification documents and may instead be held liable. Shenzhen has already seen multiple precedents in which credit repair intermediaries were convicted of fraud.
The second category is agency-assisted insurance surrender and agency-assisted rights protection. These illicit operations use full-refund insurance surrender and suspension of interest with deferred repayment as bait, charging exorbitant fees while in fact inciting consumers to fabricate grounds for complaints and engage in malicious repeated petitioning. Once consumers sign agency agreements, their personal information is resold, and they may also be placed on watch lists by financial institutions because of false complaints, affecting their future access to credit. From a civil law perspective, such agency contracts are usually held invalid by courts for violating public order and good morals, and fees already paid may be claimed for restitution; however, consumers who themselves participated in falsification cannot escape corresponding liability.
The third category consists of illegal stock recommendations and fraudulent investment platforms disguised as “wealth management courses” and “financial literacy education.” During the awareness week, “Little Animals’ Financial Literacy Course,” aimed at children, precisely highlights the lack of financial literacy education for adults. If a platform lacks a financial license but promises guaranteed principal and high returns, it may fall under Article 176 of the Criminal Law, the crime of illegally absorbing public deposits, or Article 192, the crime of fund-raising fraud; investors may report to the public security authorities and, pursuant to Article 148 of the Civil Code, request rescission of the investment contract and return of the principal on the ground of fraud.
Rights Protection Paths for Financial Consumers in Shenzhen: How to Choose Among Complaints, Mediation, and Litigation
When encountering a financial consumer dispute in Shenzhen, many people's first instinct is to call customer service, and after being given the runaround, they simply give up. In fact, the law provides three parallel avenues, and choosing the right order can save a great deal of time.
The first step is to file a complaint with the headquarters of the financial institution and retain the ticket number and call recordings. Under the Measures for the Administration of Consumer Complaints in the Banking and Insurance Sectors, the institution shall handle the complaint and notify the complainant within 15 days; where the circumstances are complex, this period may be extended to 30 days. At this stage, the key is to preserve evidence: contracts, transfer records, chat screenshots, promotional pages, and especially WeChat voice messages in which sales personnel promise returns.
The second step is to file a complaint with the regulatory authorities. In Shenzhen, it can be submitted to the Shenzhen Regulatory Bureau of the National Financial Regulatory Administration or the People's Bank of China Shenzhen Branch, or filed online through the Financial Consumer Protection Service Platform. A regulatory complaint does not directly result in compensation, but it can create pressure, and many institutions will proactively negotiate after regulatory intervention. It should be noted that when filing a complaint, you should focus on the facts of the institution's violations rather than simply stating that you lost money, as the latter can easily be deemed to mean that the investment risk is borne by you.
The third step is litigation or arbitration. Financial contracts usually provide for arbitration clauses, so the dispute resolution method must first be confirmed. In litigation, Shenzhen courts tend to handle financial consumer protection cases with increasing refinement, focusing on suitability obligations, the validity of standard-form clauses, and the elements of fraud. If the amount involved is relatively small, the small claims procedure may be considered; it provides a first-instance final judgment and a shorter timeframe.
Lawyer's suggestion: Turn financial education into actionable legal steps.
The bustle of Awareness Week will pass, but the risks will not. For ordinary people, more important than memorizing a few anti-fraud slogans is embedding legal steps into everyday financial behavior.
First, maintain reflexive vigilance against any promise of guaranteed principal and high interest, and preserve the evidence. Under Article 148 of the Civil Code, where one party, by fraud, causes the other party to perform a civil juristic act contrary to its true intention, the defrauded party has the right to request rescission. The right of rescission is subject to a one-year preclusive period, running from the date the defrauded party knew or should have known of the ground for rescission; if delayed too long, the right is extinguished.
Second, be cautious about signing any agreement for agency rights protection or debt optimization. Such contracts often provide for high service fees and restrict consumers from filing complaints themselves; once signed, they instead put the consumer in a passive position. If already signed, one may assert that the contract is invalid and demand a refund of the fees.
Third, elderly people and new urban residents should make good use of age-friendly protection rules. The regulatory measures require institutions to fulfill stricter disclosure obligations when selling high-risk products to elderly people; if a bank fails to do so, elderly people and their family members may rely on this to assert that the institution is at fault. Some districts in Shenzhen have piloted diversified mediation of financial disputes; after a mediation agreement is judicially confirmed, enforcement may be applied for, at a lower cost than litigation.
Guangdong Zhiming Law Firm has long handled financial consumer rights protection, wealth management disputes, and financial cases involving large numbers of people. We have observed a pattern: parties who succeed in defending their rights are often not those who understand the law best, but those who preserve evidence earliest and know most clearly whom to turn to. Financial education brings knowledge to service stations and villages, while what lawyers must do is translate that knowledge into actionable legal steps and help clients find the shortest path among complaints, mediation, and litigation.